Bellevue, Washington
Homeowners Insurance in Bellevue
Bellevue homes range from downtown high-rise condos to large houses in Somerset and Bridle Trails, and they need different policies. We quote an HO-3 or an HO-6 condo policy with several carriers, set limits by what it costs to rebuild and what you own, and add the pieces Bellevue owners usually miss: valuables, higher liability, earthquake and water backup.
Updated for 2026 · Served from our Kirkland office · English · Русский
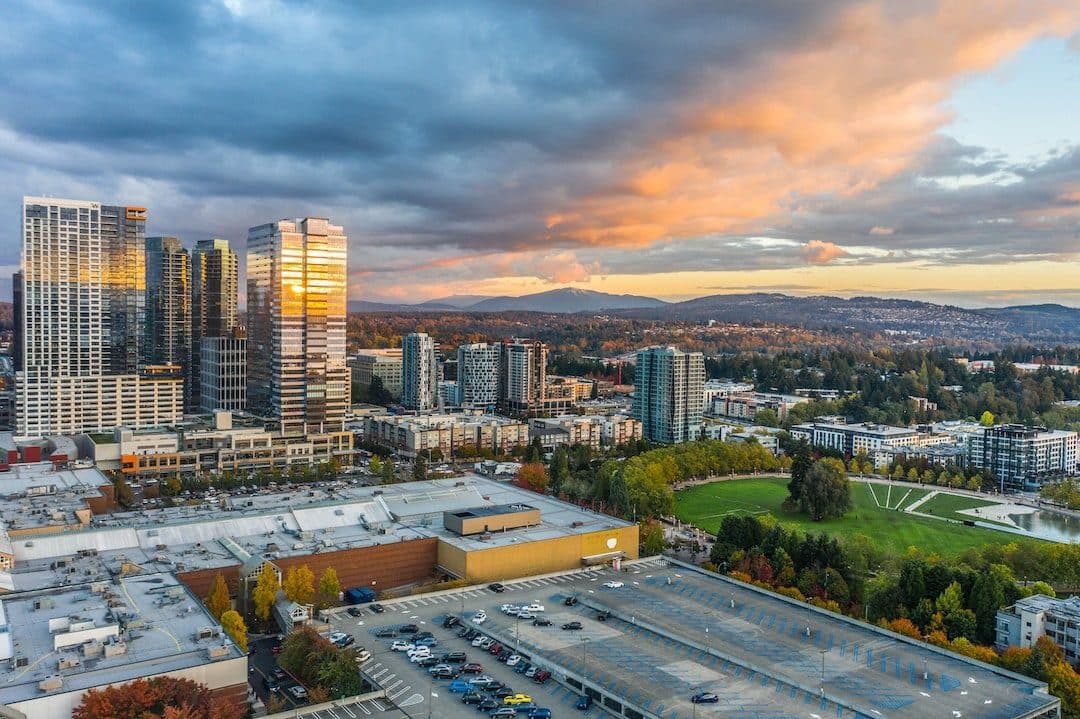
Condos in Downtown Bellevue and the Spring District
In a tower the association's master policy insures the structure, and your HO-6 starts where it stops. Ask for the master policy summary: if it covers the building as originally built, your HO-6 has to pay for upgraded floors, cabinets and fixtures; if it covers improvements too, you need less. The master policy deductible matters as much as yours, because associations often pass it to the owner whose unit caused the loss, and for water damage in a high-rise that can be tens of thousands of dollars. We size loss assessment coverage to that deductible and check that water damage from a unit above is covered the way you expect.
Larger homes: limits that keep up with the house
Houses in West Bellevue, Somerset, Bridle Trails and Newport Shores often have custom finishes that a standard replacement cost estimate undervalues. We go through square footage, construction quality, and features such as a wine room, a home theater or a detached guest house, and ask the carrier for a rebuild estimate at that level. Where it is offered, extended or guaranteed replacement cost protects you when the estimate turns out low. If the house is worth well beyond a standard policy, we look at carriers that write high-value homes and compare them with a standard policy plus endorsements.
Jewelry, art, watches and other valuables
A standard policy pays only a small amount for stolen jewelry, watches, furs, silverware or collectibles, often a few thousand dollars per category, no matter what they are worth. Scheduling an item on its own, with an appraisal or a receipt, covers it for an agreed value and usually covers loss as well as theft, without the main deductible. We go through what you would actually want replaced and schedule it item by item, which costs far less than most owners assume.
Liability and an umbrella policy
Personal liability on a homeowners policy usually starts at $100,000 to $300,000 and pays when a guest is hurt at your home, your dog bites someone or you accidentally damage a neighbor's property. A pool, a trampoline, a dock on Lake Sammamish or teen drivers in the household raise the exposure, and a judgment can follow your income and savings. We raise the liability limit on the homeowners policy and quote an umbrella that sits on top of both home and auto, which is usually cheapest when the home and the cars are with the same carrier.
Trees, windstorms, earthquakes and water
Bellevue neighborhoods are full of tall firs, and the Puget Sound windstorm season brings them down every year. A tree that falls on the house is covered, but removal limits for trees that land on the lawn are usually small. The Seattle Fault zone crosses south Bellevue, and earthquake damage is excluded from every standard policy, so we quote earthquake coverage separately with its percentage deductible. Flood is also excluded; homes near Kelsey Creek, Coal Creek or the Mercer Slough should check the FEMA flood map and price a policy. Sewer and drain backup needs its own endorsement, which matters for any house with a finished basement.
Renting out a home, a room or an ADU
A homeowners policy assumes you live in the house. If you move out and rent it, it needs a landlord (dwelling fire) policy instead. If you rent a room or a backyard cottage, or list the place on a short-term rental platform, tell the carrier: some policies exclude business activity and most limit coverage for renters' belongings and injuries to paying guests. We match the policy to how the property is used, so a claim is not denied because of a rental nobody mentioned.
Getting a Bellevue homeowners quote
Send the address, the year the roof was replaced, any recent remodel, the HOA master policy summary for a condo, and your current declarations page if you have one. We quote several carriers for the same coverage and show you the difference line by line. For a purchase we send proof of insurance to your lender and escrow before closing. Call (425) 610-6909 or use the quote form; our office is in Kirkland, a short drive up I-405 from Bellevue, and our agents speak English and Russian.
Other coverage in Bellevue
Homeowners Insurance in nearby cities
Google reviews
What clients say about their homeowners insurance.
Alexandra and Boris helped us find a Condo + Auto + Umbrella bundle with the same coverage, saving us over $400. They also spent more than 4 hours answering all our questions and educating us on which claims are effective and, more importantly, which ones are not.
Evgeny K. Absolute Insurance Solutions has been extremely knowledgeable and helpful to me and my family in a wide array of problems and complicated matters. Could not be more pleased with the interactions and results I’ve received.
roman V. We are really happy we found good honest people that are saving us a lot of money and actually take the time to explain how insurance works. Thank you Irina, Boris and the Absolute Team!
Nina G.
FAQ
Homeowners Insurance in Bellevue: your questions.
How much does homeowners insurance cost in Bellevue, WA?
What does an HO-6 condo policy cover in a Bellevue high-rise?
How much liability coverage should a Bellevue homeowner carry?
Does homeowners insurance cover earthquakes in Bellevue?
Homeowners Insurance in Bellevue, quoted by a local agent.
Call us or fill in the quote form. A local agent will come back with prices from several carriers.